$55 Billion Shield: What Nigeria’s 18-Year Reserve High Really Means

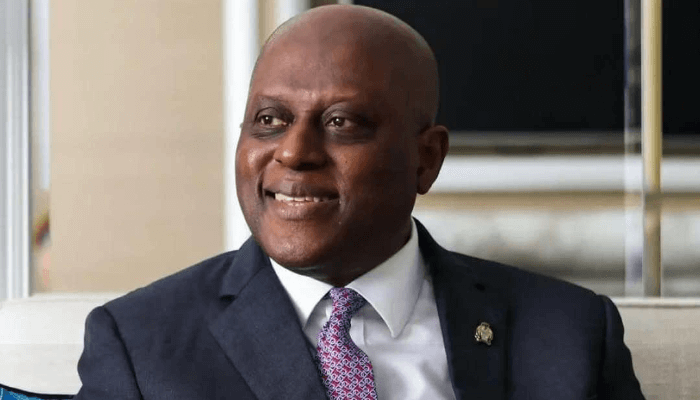
Nigeria’s foreign reserves crossing $55 billion, the highest level in over 18 years as announced by Central Bank Governor Yemi Cardoso after the 307th Monetary Policy Committee meeting, is far more than a statistical milestone. It is a statement about the health, credibility and breathing space of the economy. In any economy, foreign reserves function as the country’s savings in foreign currency, held in dollars, euros, gold and other internationally accepted assets, and they exist for a practical reason. The world does not trade in naira, cedi or any local currency for critical transactions. A nation must pay for fuel imports, industrial machinery, external debt service and essential goods in hard currency, and when that hard currency runs out, the entire economic system faces suffocation through exchange rate collapse, import shortages and loss of confidence.
The first major implication of this rise is confidence and currency stability, which Cardoso directly linked to reforms in the foreign exchange market. He described the previous regime of multiple exchange rates as dysfunctional, where access and connections determined what rate you got, costing the country an estimated 2.2 percent of GDP in implicit subsidies and creating room for arbitrage where some profited at the expense of others. By closing that gap and allowing a more unified, market-reflective rate, the Central Bank has reduced the leakages that drained reserves in the past. A reserve level of over $55 billion, up from $54.08 billion on September 3 and well above the projected $51.04 billion for all of 2026, tells investors, rating agencies and speculators that the central bank now has greater firepower to smooth volatility, narrow the gap between official and parallel markets, and assure foreign investors that they can repatriate their funds.
The second implication is that reserves act as an insurance buffer against external shocks, which is particularly important for an economy like Nigeria that still relies heavily on crude oil for dollar inflows. International reserves determine how many months a country can pay for imports if export revenues collapse, or how it can meet Eurobond repayments and other external obligations when global markets tighten. Rebuilding from years of depletion to an 18-year high therefore restores a crucial safety net. Cardoso’s reference to diaspora contributions is significant in this interpretation because it suggests a deliberate attempt to diversify the sources of dollar accumulation beyond oil, making the reserve growth more resilient than in previous oil boom cycles.
However, the third and more complex interpretation is the cost of accumulating those reserves and the policy trade-offs involved. Reserves do not grow in a vacuum. They are often built by keeping monetary conditions tight enough to attract and retain portfolio flows. This context explains why, in the same meeting where the reserve milestone was announced, the MPC cut the Monetary Policy Rate by 350 basis points to 23 percent but simultaneously retained a very high Cash Reserve Requirement of 45 percent for Deposit Money Banks and recalibrated the asymmetric corridor around the MPR to +50/-300 basis points. Cardoso described this as an operational reset to enhance transmission and support a transition to inflation targeting, rather than a change in stance. In plain terms, the bank is trying to make policy more effective while still keeping liquidity tight, because loosening too quickly could lead to capital outflows and reverse the reserve gains. The risk is that high reserves held at the expense of domestic credit can stifle the real sector, as banks have less to lend to businesses.
Ultimately, the final implication for any economy is that reserves are a measure of credibility, not of development itself. A high reserve number buys time, trust and stability, but it does not build factories, create jobs or lower food prices on its own. It creates the conditions under which those things can happen by reducing exchange rate panic and imported inflation. The real test for Nigeria now is not whether it can cross $55 billion, but how sustainably that level was achieved and how it will be used. If the buffer is deployed to maintain stability while productive reforms take hold, it becomes a launchpad. If it merely sits as a trophy number while the domestic economy remains starved of credit and productive capacity, then it remains just a number in a press conference.